Fitted Instantaneous Forward Rate 5 Years Hence (THREEFF5)

2026-09-25: 5.0227
Updated: Sep 29, 2026 2:04 PM CDT
Next Release Date: Not Available
2026-09-25:  5.0227  
2026-09-24:  5.0249  
2026-09-23:  4.9526  
2026-09-22:  4.8307  
2026-09-21:  4.8496  
View All

Units:

Percent,
Not Seasonally Adjusted

Frequency:

Daily

Fullscreen
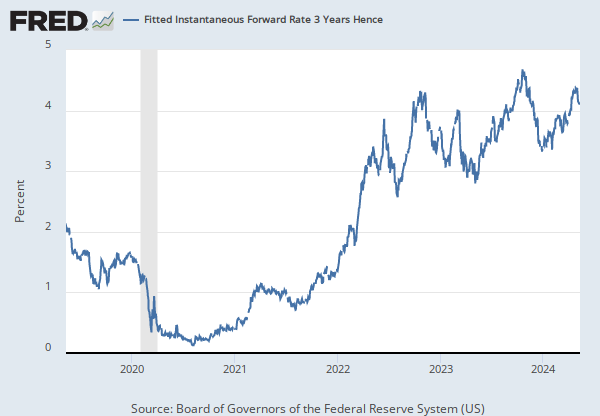
Notes

Source: Board of Governors of the Federal Reserve System (US)  

Release: An Arbitrage-Free Three-Factor Term Structure Model and the Recent Behavior of Long-Term Yields and Distant-Horizon Forward Rates  

Units:  Percent, Not Seasonally Adjusted

Frequency:  Daily

Notes:

Kim and Wright (2005) produced this data by fitting a simple three-factor arbitrage-free term structure model to U.S. Treasury yields since 1990, in order to evaluate the behavior of long-term yields, distant-horizon forward rates, and term premiums. For the full paper, please go to http://www.federalreserve.gov/pubs/feds/2005/200533/200533abs.html

Suggested Citation:

Board of Governors of the Federal Reserve System (US), Fitted Instantaneous Forward Rate 5 Years Hence [THREEFF5], retrieved from FRED, Federal Reserve Bank of St. Louis; https://fred.stlouisfed.org/series/THREEFF5, .

Release Tables

An Arbitrage-Free Three-Factor Term Structure Model and the Recent Behavior of Long-Term Yields and Distant-Horizon Forward Rates

Back to Top