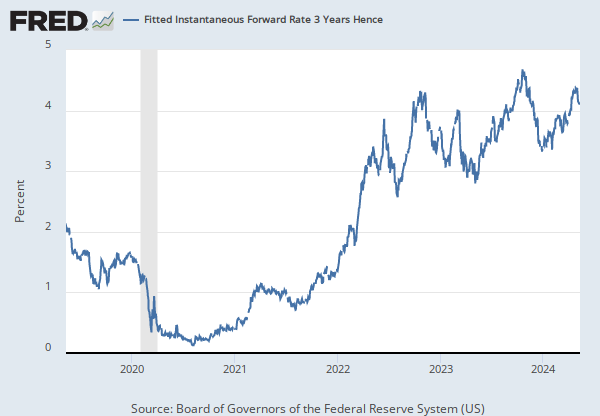
Fitted Instantaneous Forward Rate 1 Year Hence (THREEFF1)

2026-10-09: 4.8831
Updated: Oct 13, 2026 2:03 PM CDT
Next Release Date: Not Available
2026-10-09:  4.8831  
2026-10-08:  4.8656  
2026-10-07:  4.8940  
2026-10-06:  4.9154  
2026-10-05:  4.9536  
View All

Units:

Percent,
Not Seasonally Adjusted

Frequency:

Daily

Fullscreen

Notes

Source: Board of Governors of the Federal Reserve System (US)  

Release: An Arbitrage-Free Three-Factor Term Structure Model and the Recent Behavior of Long-Term Yields and Distant-Horizon Forward Rates  

Units:  Percent, Not Seasonally Adjusted

Frequency:  Daily

Notes:

Kim and Wright (2005) produced this data by fitting a simple three-factor arbitrage-free term structure model to U.S. Treasury yields since 1990, in order to evaluate the behavior of long-term yields, distant-horizon forward rates, and term premiums. For the full paper, please go to http://www.federalreserve.gov/pubs/feds/2005/200533/200533abs.html

Suggested Citation:

Board of Governors of the Federal Reserve System (US), Fitted Instantaneous Forward Rate 1 Year Hence [THREEFF1], retrieved from FRED, Federal Reserve Bank of St. Louis; https://fred.stlouisfed.org/series/THREEFF1, .

Release Tables

An Arbitrage-Free Three-Factor Term Structure Model and the Recent Behavior of Long-Term Yields and Distant-Horizon Forward Rates

Back to Top